A systematic options strategy. Verified daily results.

One systematic options strategy, run on the author's own account. Results are published every trading day, only after the US close, and are never revised. The single benchmark is the S&P 500.

Last session2 Nov
−12.81%
Convexa strategy, author's own account
SPY−0.48%
Excess−12.33 pp
1 week · 30 Oct – 2 Nov−12.81%SPY −0.48% 1 month · 2–2 Nov−12.81%SPY −0.48% Since inception · 5 Aug – 2 Nov−8.23%SPY −2.27% Current drawdown from peak−50.52%From most recent high

Fall in account value from its most recent high to today. Full risk history, including the maximum drawdown since inception, is on the Performance page.

Vol Lab · Week 45 · Session of Mon 2 Nov 2026

The volatility surface behind the decisions

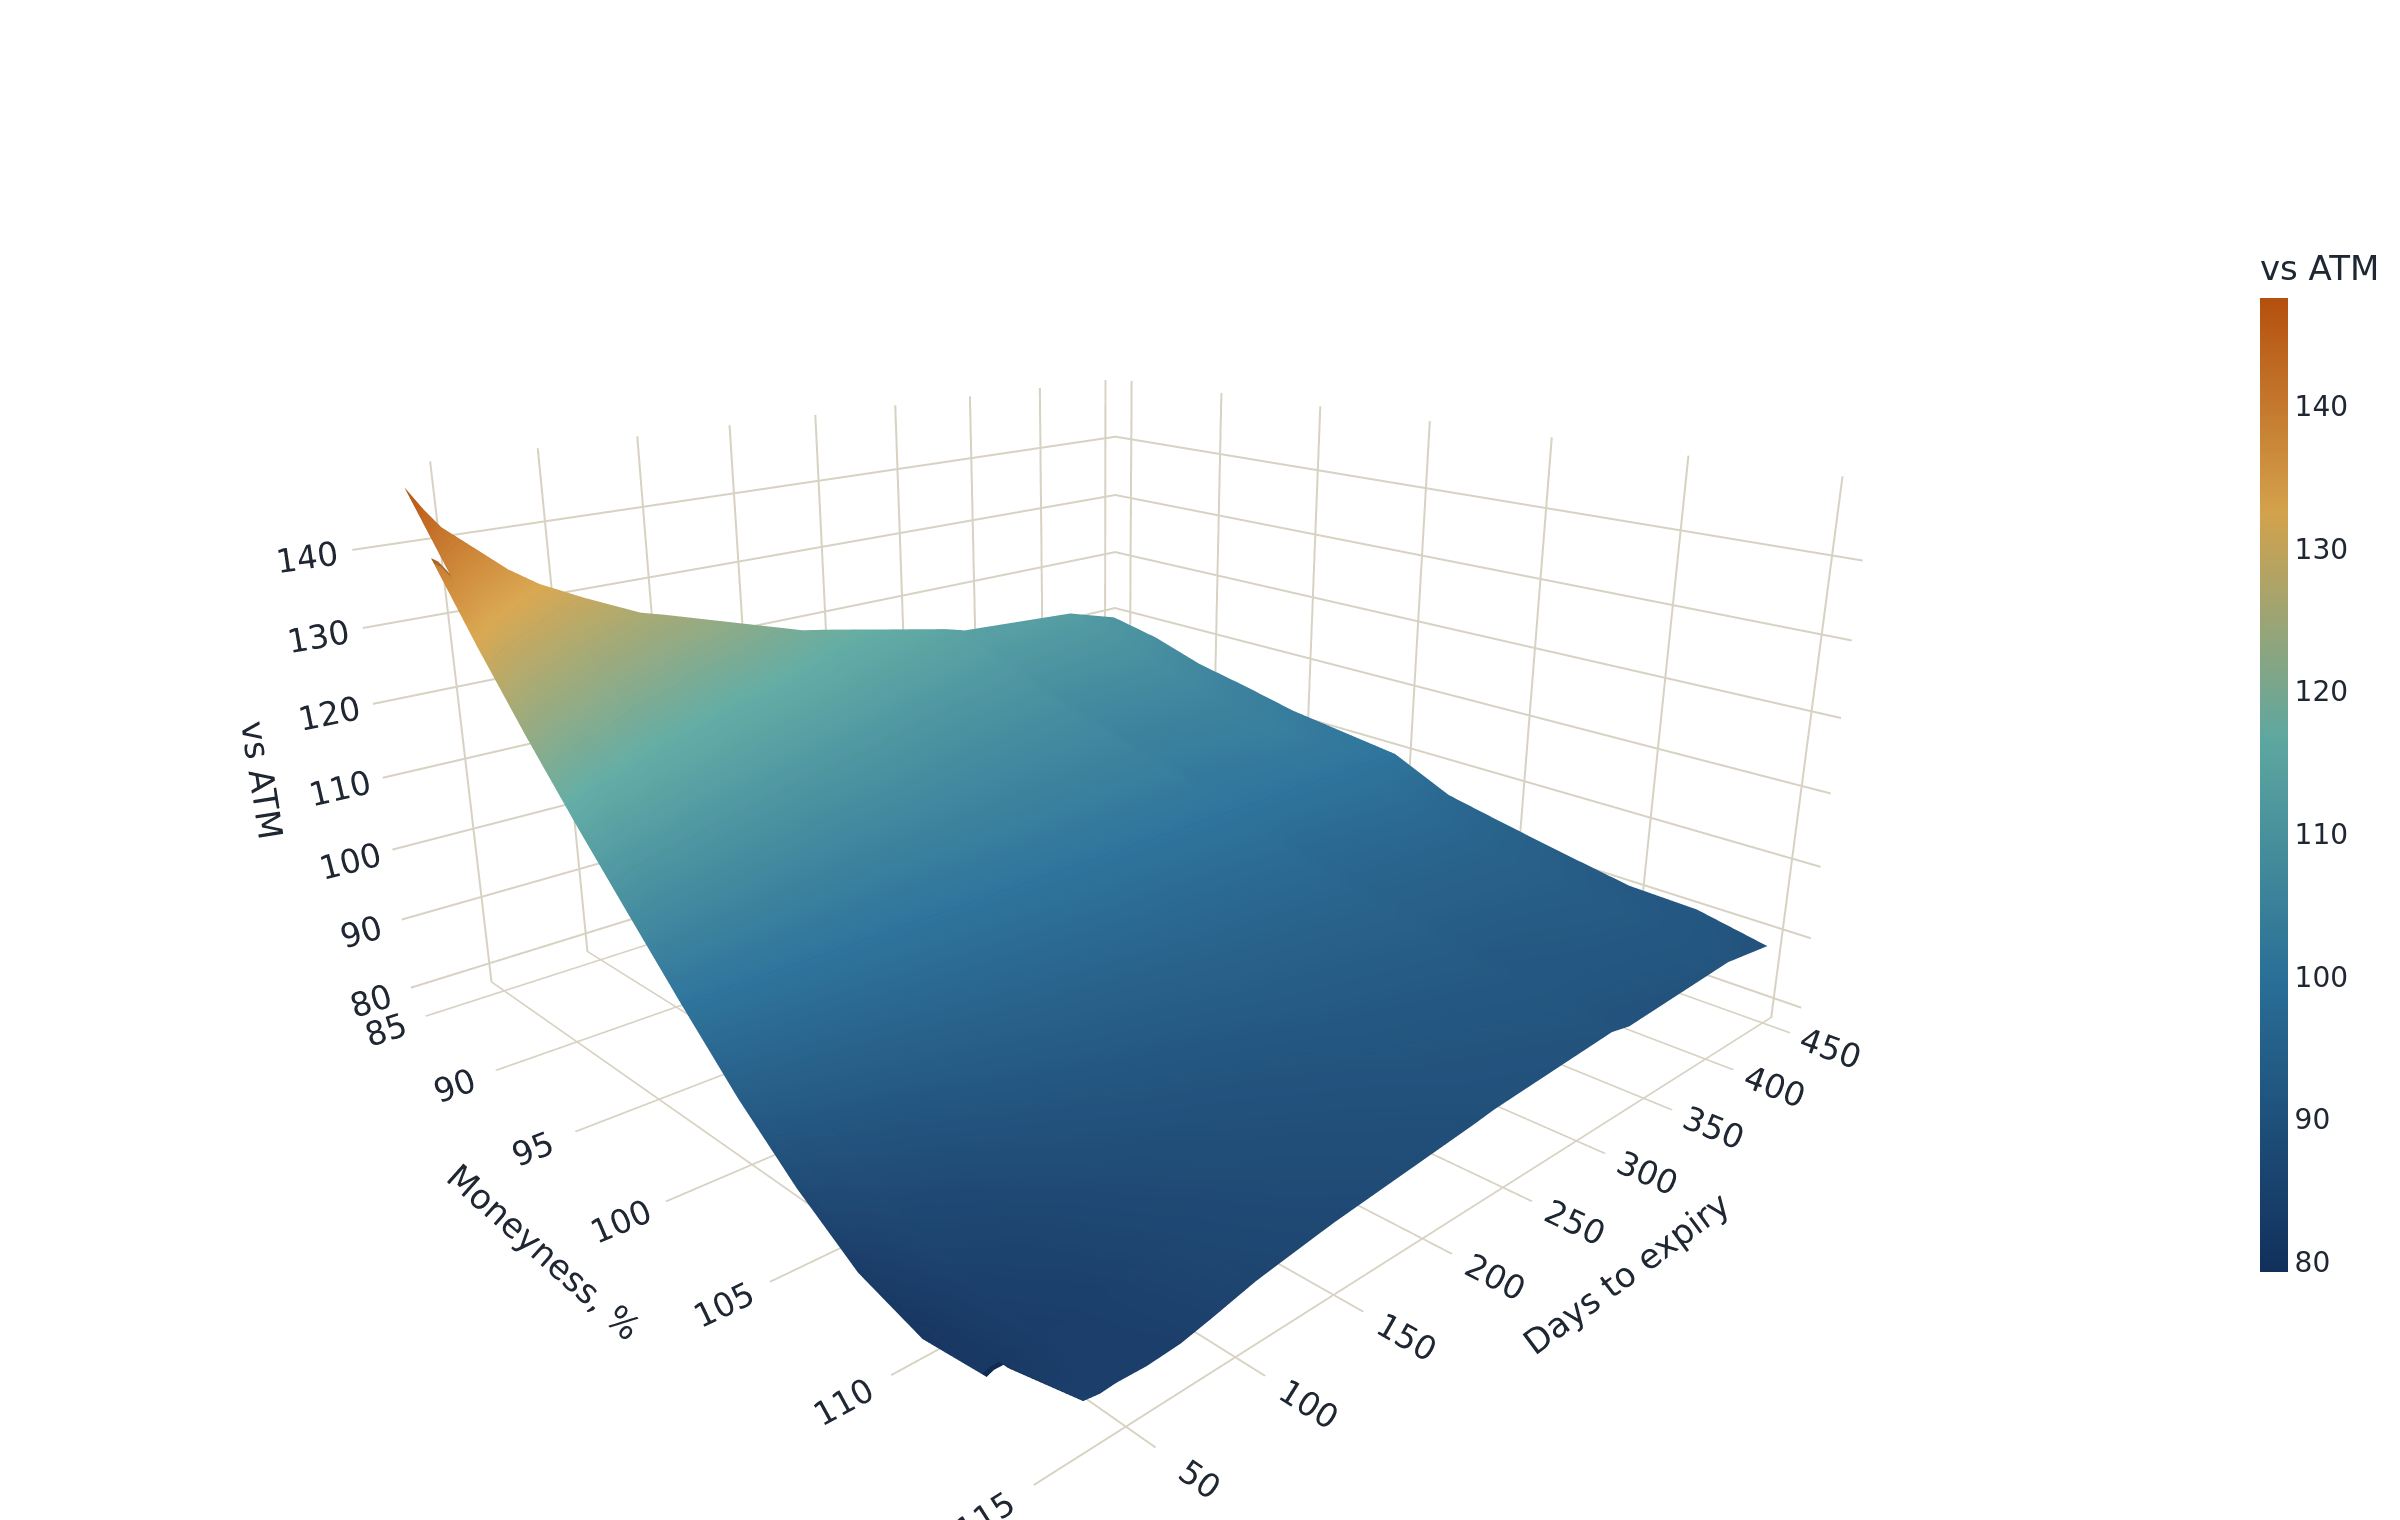
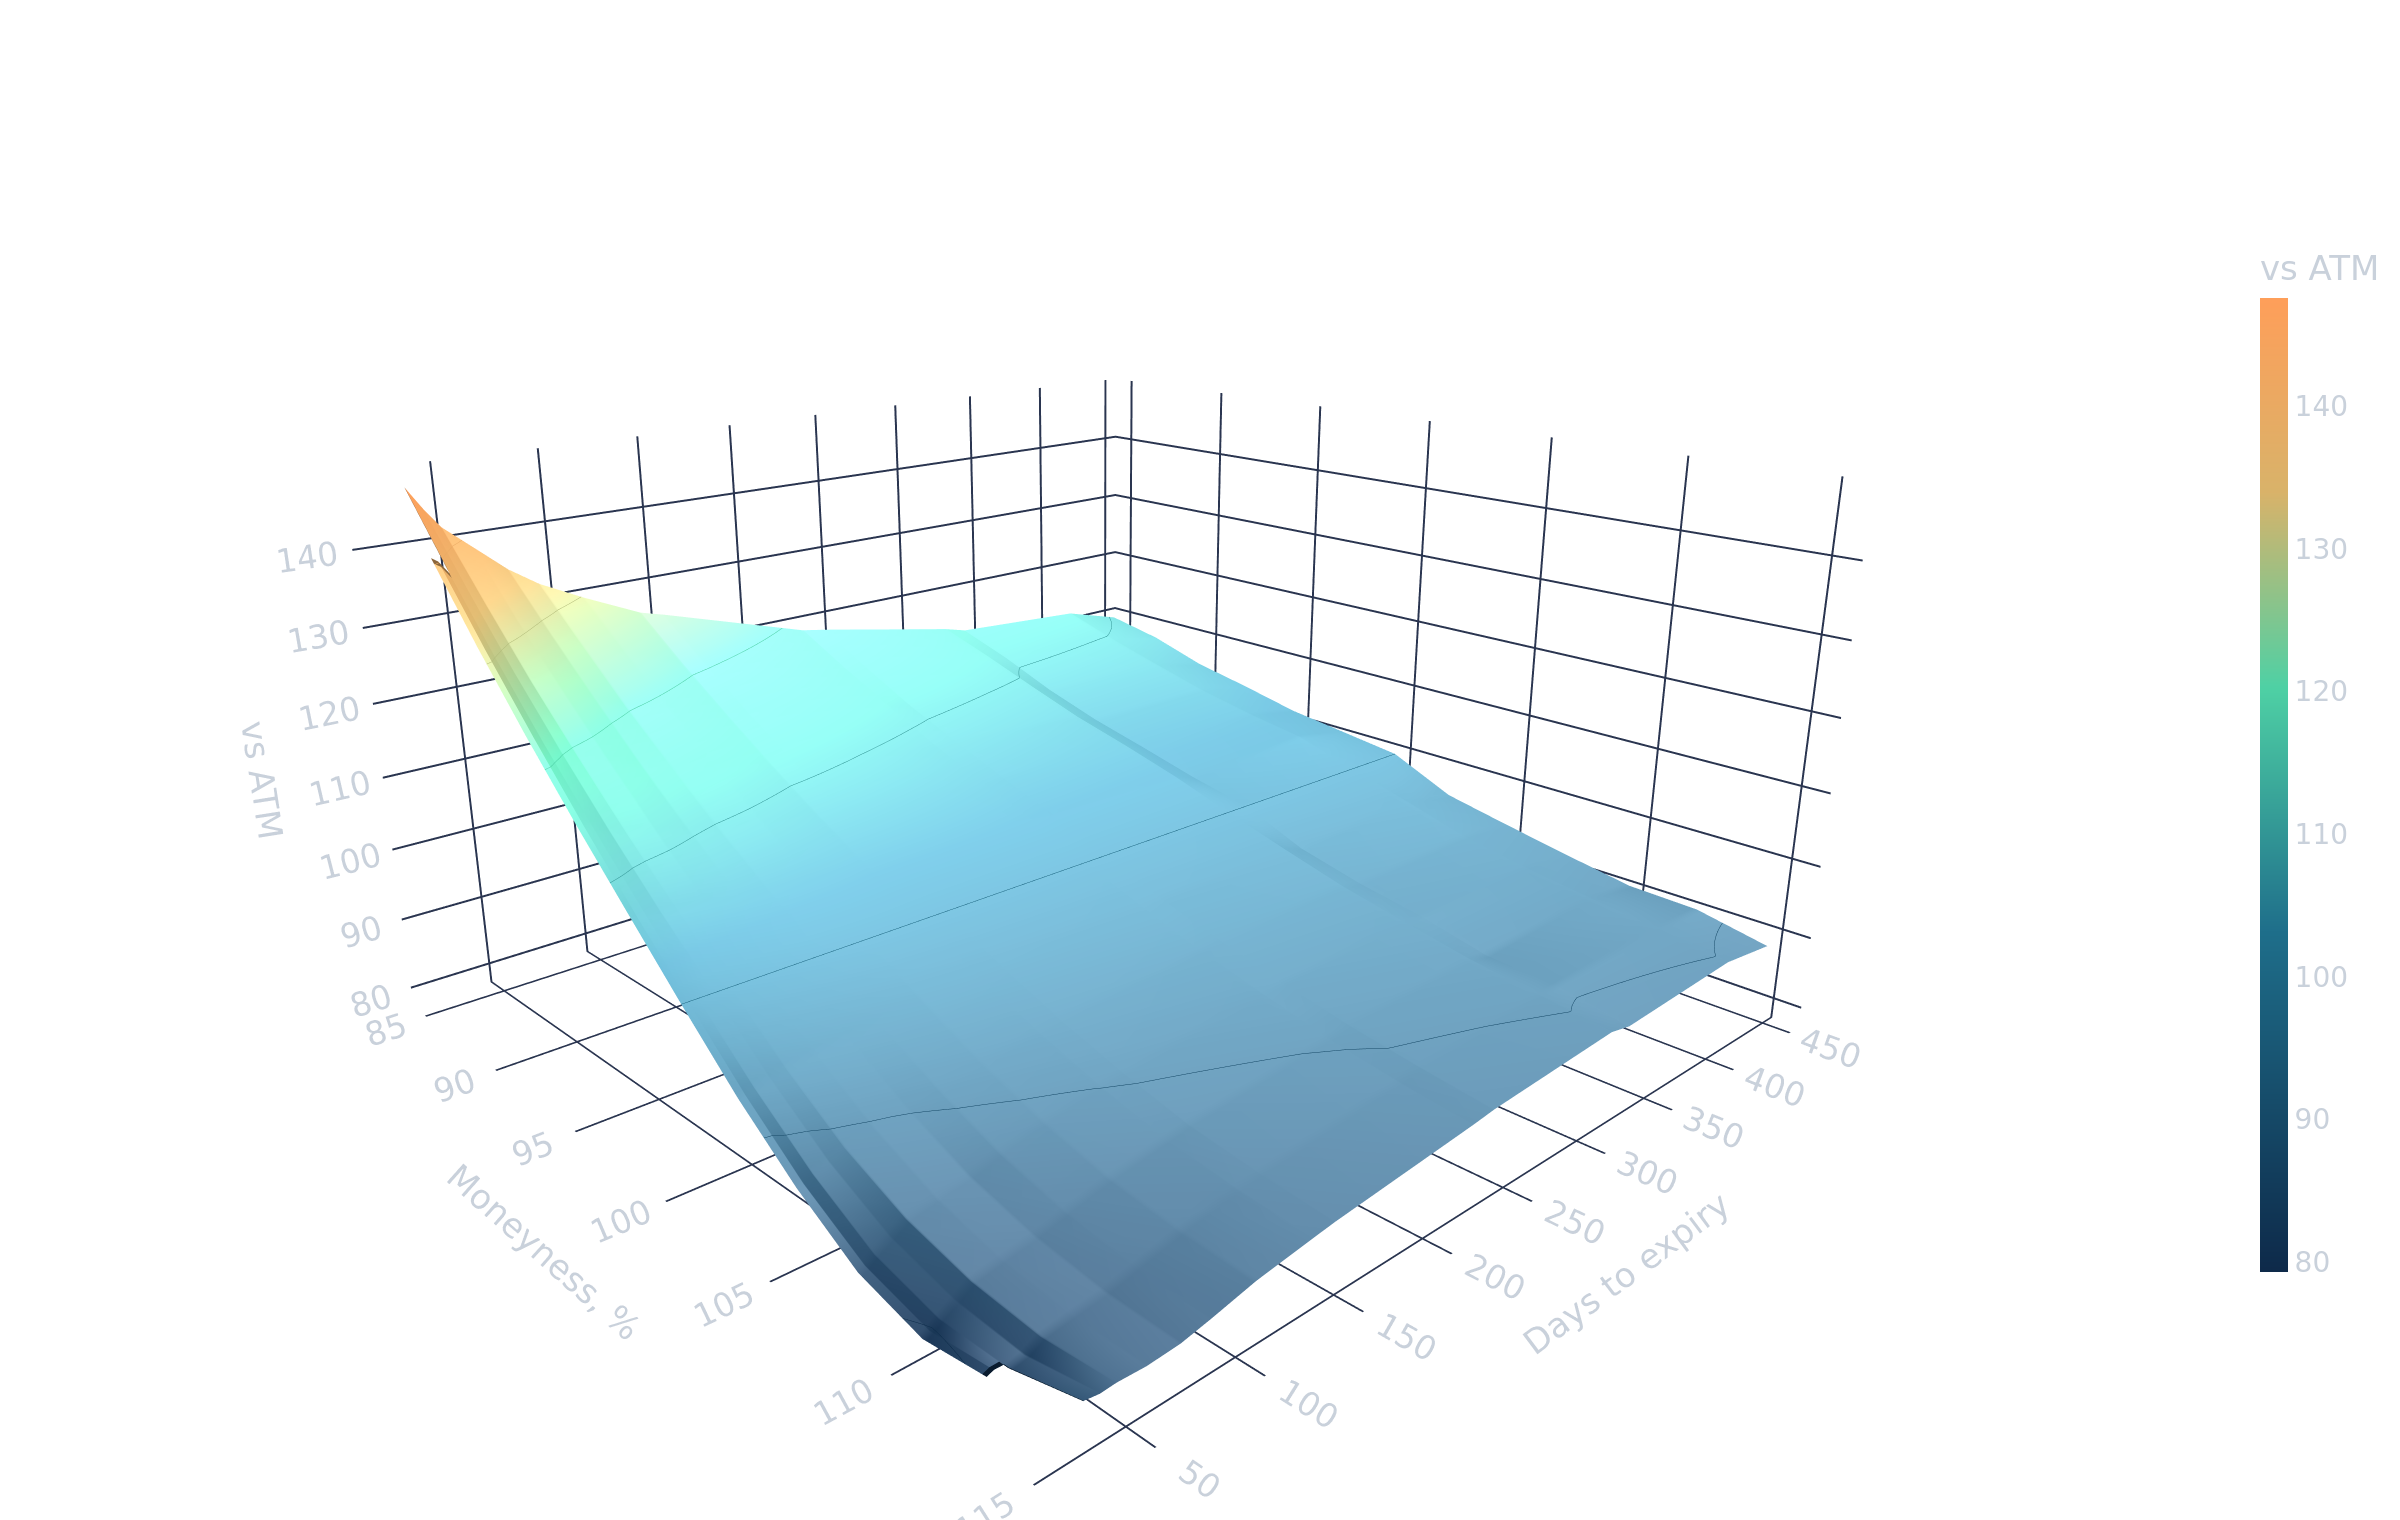
QQQ implied-volatility surface, session of 2 Nov 2026, shown relative to at-the-money (ATM = 100).

Options data published with a one-session delay (after 9:30 a.m. New York time the next trading day).

Open full Vol Lab →
Expected move · to 6 Nov±3.30%▼ −0.1 pp to nearest expiry (Friday weekly); since 30 Oct
Skew index · 30D28.9session close
VIX / VIX3M0.979Regime: Elevated
VXN30.89▲ +2.4 since 30 Oct
QQQ implied-volatility surface relative to ATM = 100, by moneyness and days to expiryQQQ implied-volatility surface relative to ATM = 100, by moneyness and days to expiry
Smile by maturity · relative to ATM
Expected move by horizon · IV-based · 30 Oct vs 2 Nov
Cboe SKEW · 1 year
VIX / VIX3M · 1 year · 0.85 line
What moved this week

Elevated regime

VIX/VIX3M closed at 0.979, above the 0.95 line. Normal on Friday, Elevated since Monday.

Downside cheapened most

The one-month downside wing cheapened more than at-the-money options since 30 Oct; the expected move to 6 Nov is ±3.30%.

Source: own calculations. Session of 2 Nov 2026, published Tue 3 Nov after 9:30 a.m. New York time. Expected move KPI to nearest expiry (Friday weekly) = ATM straddle ÷ spot × 100%; horizon chart = ATM IV (%) × √(days/365); skew index = 30D put−call skew ÷ ATM vol × 100.

Editor's Note · 2 November 2026

Volatility rose as the technology decline extended: the account fell 12.81%

Implied volatility rose for a second session, even though the index fell less than on Friday. VIX rose 1.73 points to 21.15 and VXN 2.39 points to 30.89; 30-day QQQ implied volatility (own calculations) rose from 25.11% to 27.72%. At the 30-day horizon, 25-delta puts gained 2.2 volatility points and 10-delta puts 2.65 points, against 1.76 points for 25-delta calls; the 25-delta skew widened to 7.68 points. The skew index eased to 27.7 from 28.8, because the overall level of volatility again rose faster than the skew itself. The front of the curve rose most: VIX9D/VIX moved to 1.062 from 0.991 and VIX/VIX3M to 0.979 from 0.935. On the Convexa scale the regime moved from Normal to Tense, with the event and negative-gamma modifiers: QQQ closed 4.92% below the model zero-gamma level of 716.34.

The account closed the session 12.81% lower, against a 0.48% decline in SPY. The main loss again came from the short long-dated puts: as QQQ fell and put volatility rose, they gained more in value than the day's total loss. It was partly offset by the short long-dated calls, which lost value in the decline, by the long lower-wing puts, and by short-dated protection opened during the session in the 3 and 9 November expiries. The 2 November short-dated protection and calls expired worthless. During the session the upside wings were also moved to the 3 and 9 November expiries. This was the first session of the week and of the month, so week-to-date and November-to-date results equal the session: −12.81% against −0.48% for SPY. Since the start of the public record on 5 August the result was −8.23%, against −2.27% for SPY.

At the close the weekly QQQ straddle priced a move of ±3.30% to the Friday 6 November expiry (range 658.62–703.56), against ±3.20% a session earlier. QQQ closed 0.19% above its 200-day average (679.82). Ahead were the JOLTS report on 3 November at 10:00 ET, the U.S. midterm elections and AMD results after the close the same day, the ISM services index on 4 November, productivity and costs and weekly jobless claims on 5 November at 08:30 ET, and the October employment report on 6 November at 08:30 ET.

Full session record →
Editor’s Note reflects the author’s market perspective at the time of publication and should be read as commentary, not investment advice.
Growth of 1,000 · since 5 Aug
Convexa SPY

VAMI (Value-Added Monthly Index) shows what 1,000 invested on day one would be worth today: 1,500 would mean +50% since inception (total return, not annualized).
Calculation: VAMI starts at 1,000 and each day VAMIt = VAMIt−1 × (1 + rt), where rt is the published daily return.

Volatility regime
Elevated
CalmNormalElevatedStress

VIX/VIX3M closed at 0.979, above the 0.95 line. Normal on Friday, Elevated since Monday.

Risk Map · 2–6 November

Weekly risk: High. Key day Friday · 6 November

Full Risk Map →
MON 2
Moderate

The ISM manufacturing index for October came in above expectations and pointed to continued expansion. Technology shares fell as chipmakers slid, and the Nasdaq Composite ended the session lower while the Dow gained. After the close, Apple's quarterly results beat expectations, but a softer margin outlook weighed on the shares in extended trading.

MON · 2 NovModerate riskThe ISM manufacturing index for October came in above expectations and pointed to continued expansion. Technology shares fell as chipmakers slid, and the Nasdaq Composite ended the session lower while the Dow gained. After the close, Apple's quarterly results beat expectations, but a softer margin outlook weighed on the shares in extended trading.
TUE 3
High

First regular session after Apple's results. September JOLTS job openings are released at 10:00 ET. U.S. midterm elections are held; polls close between 18:00 ET and 01:00 ET, and results are reported as counting proceeds. AMD reports third-quarter results after the close.

TUE · 3 NovHigh riskFirst regular session after Apple's results. September JOLTS job openings are released at 10:00 ET. U.S. midterm elections are held; polls close between 18:00 ET and 01:00 ET, and results are reported as counting proceeds. AMD reports third-quarter results after the close.
WED 4
High

First regular session after the midterm elections and AMD's report. The ISM services index for October is released at 10:00 ET.

WED · 4 NovHigh riskFirst regular session after the midterm elections and AMD's report. The ISM services index for October is released at 10:00 ET.
THU 5
Moderate

Preliminary third-quarter productivity and costs and weekly jobless claims are released at 08:30 ET.

THU · 5 NovModerate riskPreliminary third-quarter productivity and costs and weekly jobless claims are released at 08:30 ET.
FRI 6 · KEY DAY
High

The October employment report is released at 08:30 ET. It is the main macro event of the week, and weekly QQQ options expire at the close.

FRI · 6 NovHigh riskThe October employment report is released at 08:30 ET. It is the main macro event of the week, and weekly QQQ options expire at the close.

Key day: Friday · 6 November. Editorial assessments, not predictions.

Market · Session of 2 November 2026

Latest analysis

Technical

Horizons follow section 2.9 of the methodology (price versus the average, and the five-session slope where the scale uses it).

Full analysis →
Fundamental

10-year yield eased to 4.91% on 2 November (prior 4.94%). Real 10-year 2.62%.

Full analysis →
Volatility

VIX 21.15, VXN 30.89

NDX closed at 27989.82 (−1.39%). VIX 21.15 (+1.73).

Full analysis →