Home/Vol Lab
Vol Lab · Week 43, 2026

QQQ implied volatility surface

Session of Monday, 19 October 2026. Shown relative to at-the-money (ATM = 100).

Options data published with a one-session delay (after 9:30 a.m. New York time the next trading day).

Closes 16–19 Oct 2026·Source: own calculations. Session of 19 Oct 2026, published Tue 20 Oct after 9:30 a.m. New York time. Expected move KPI to nearest expiry (Friday weekly) = ATM straddle ÷ spot × 100%; horizon chart = ATM IV (%) × √(days/365); skew index = 30D put−call skew ÷ ATM vol × 100. Surface and smile relative to ATM = 100.
Surface

Volatility vs ATM = 100

Implied volatility relative to ATM by moneyness and days to expiry. From 20 days to about 15 months, 85% to 115% moneyness.
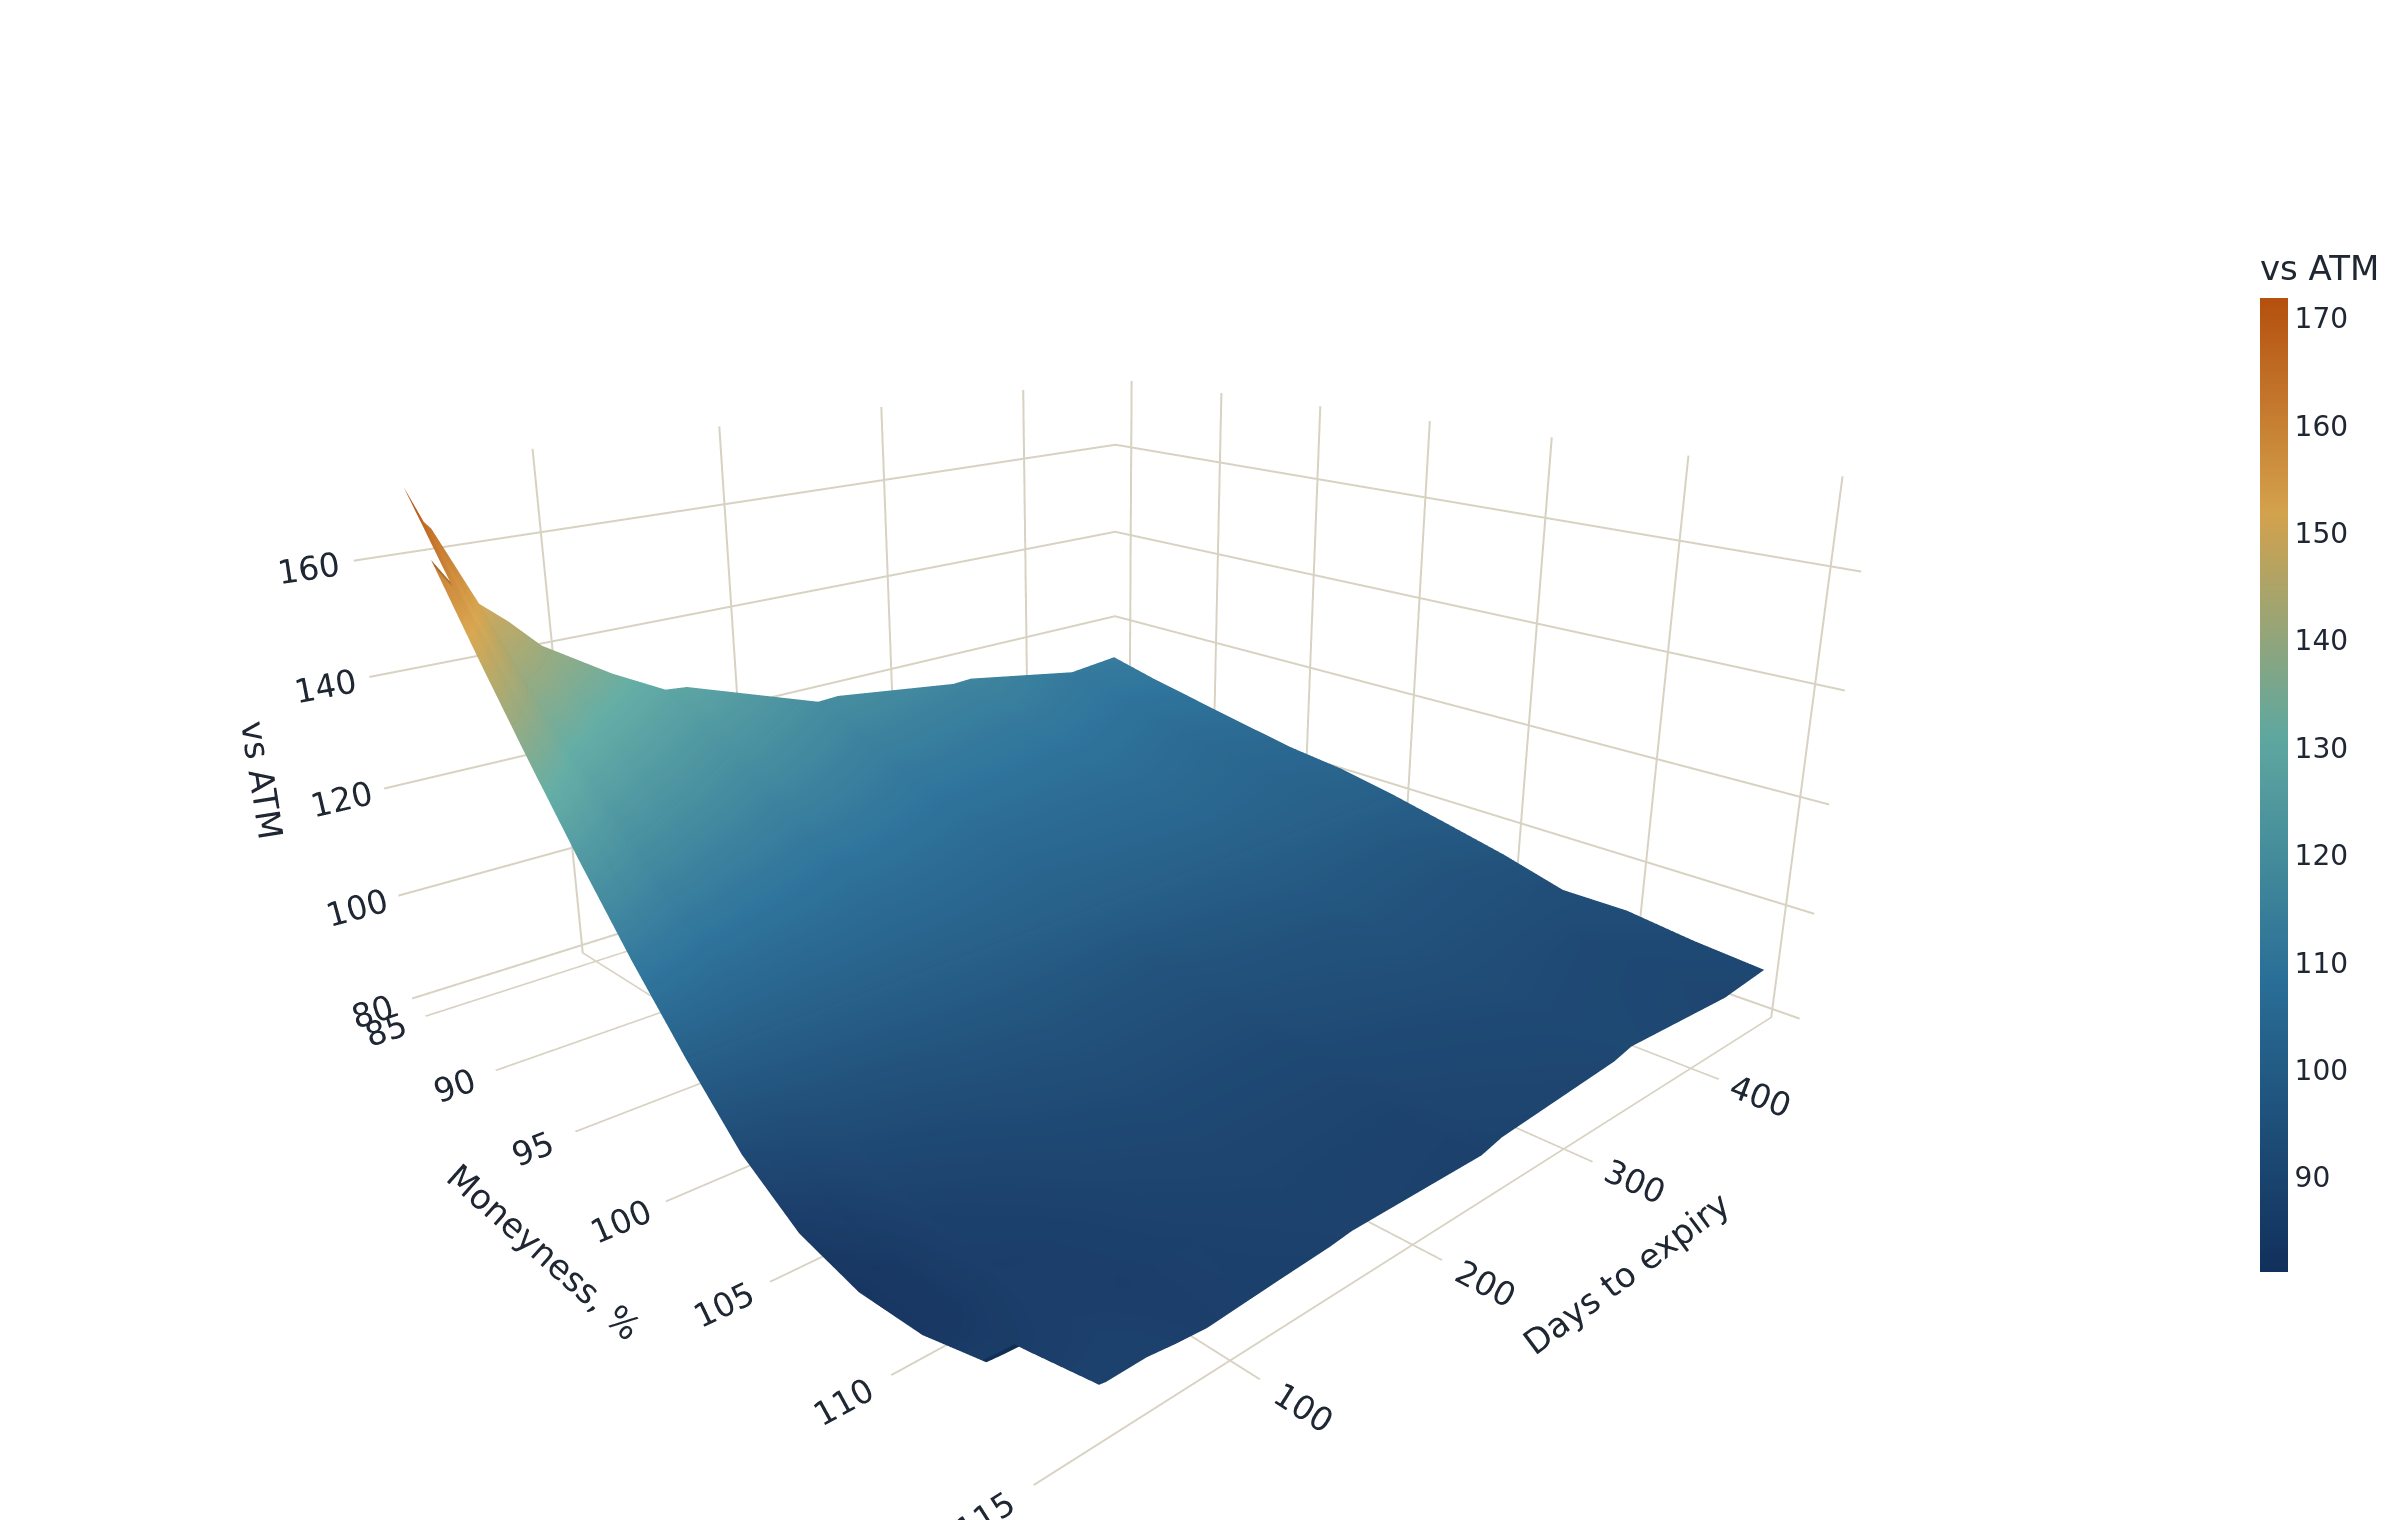
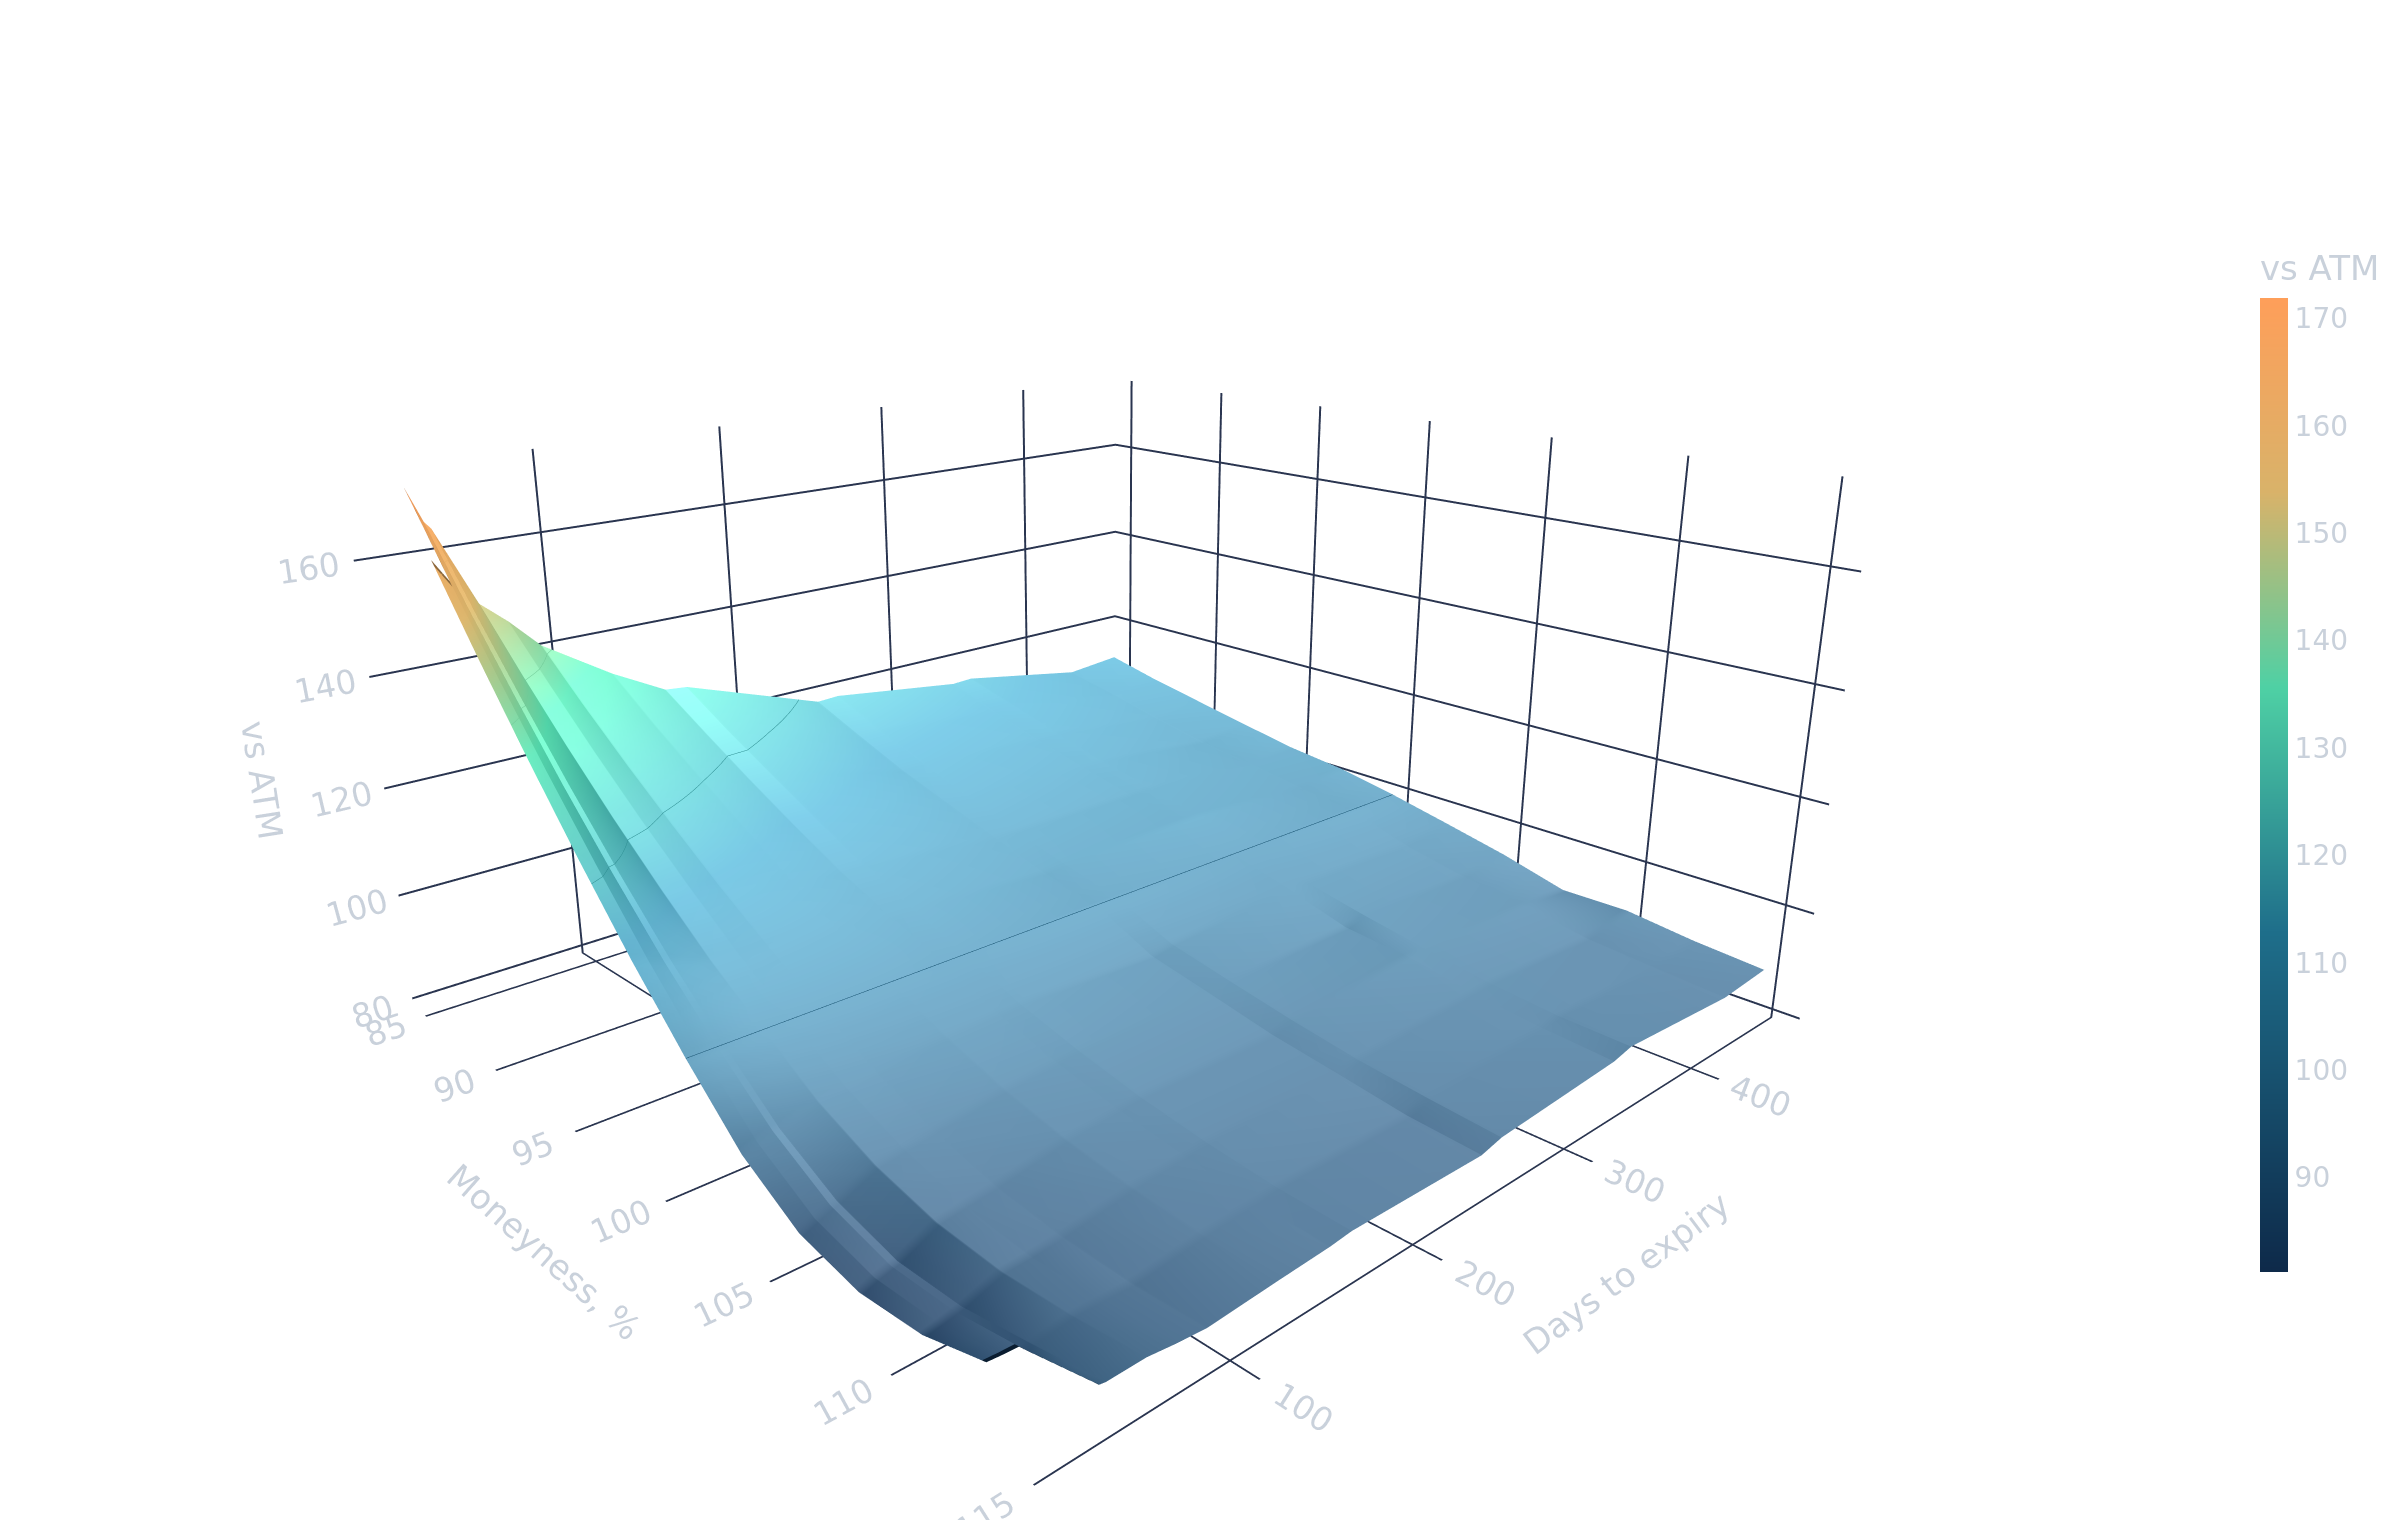
QQQ implied-volatility surface relative to ATM = 100, by moneyness and days to expiryQQQ implied-volatility surface relative to ATM = 100, by moneyness and days to expiry
Source: own calculations. Session of 19 Oct 2026, published Tue 20 Oct after 9:30 a.m. New York time. Expected move KPI to nearest expiry (Friday weekly) = ATM straddle ÷ spot × 100%; horizon chart = ATM IV (%) × √(days/365); skew index = 30D put−call skew ÷ ATM vol × 100. Surface and smile relative to ATM = 100.
Term

Expected move by horizon

ATM IV × √(days/365), each close of the week.

Skew

Cboe SKEW · 1 year

Cboe SKEW index over the last year, 5-day average; the dot is the latest close. Higher means downside protection is relatively more expensive. Source: Cboe.

Regime

VIX / VIX3M

Last year, 5-day average; the dot is the latest close. Below 0.85 reads Calm, 0.85 to 0.95 Normal, above 0.95 Elevated. Source: Cboe.

Source: own calculations. Session of 19 Oct 2026, published Tue 20 Oct after 9:30 a.m. New York time. Expected move KPI to nearest expiry (Friday weekly) = ATM straddle ÷ spot × 100%; horizon chart = ATM IV (%) × √(days/365); skew index = 30D put−call skew ÷ ATM vol × 100. Surface and smile relative to ATM = 100. Not investment advice.